Showing posts with label Finances. Show all posts

Sunday, August 30, 2020

Solar Energy: My Financial Logic is at War With My Conscience

Tesla Solar Panels


Over the past few years, solar energy has interested me to the point where I asked that our house be built to enhance the support for future solar panels on the roof. My personal financial investments have also revolved around renewable energy. And so I've recently looked into having solar panels installed on our home. In my opinion, it's not yet inexpensive from a financial standpoint. 

But from the perspective of climate change and the health of our environment, it's probably invaluable at this point. 

Here's the high level overview and some of my thoughts: 

  • One of the first things that people interested in solar look into is the Investment Tax Credit (ITC). Despite the fact that solar hasn't been so widely adopted yet, the credit seems to be already phasing out. The credit comes as a tax benefit and is computed based on the initial cost of the system. You get the full credit in year one. As you can see, residential customers have less than 3 years to get any kind of credit for adopting solar. I hope that there is a renewal of the incentives. 
    • 2016 – 2019: The tax credit remains at 30 percent of the cost of the system.
    • 2020: Owners of new residential and commercial solar can deduct 26 percent of the cost of the system from their taxes.
    • 2021: Owners of new residential and commercial solar can deduct 22 percent of the cost of the system from their taxes.
    • 2022 onwards: Owners of new commercial solar energy systems can deduct 10 percent of the cost of the system from their taxes. There is no federal credit for residential solar energy systems.

  • Solar panels have a life of somewhere between 20-25 years. But they have practically no maintenance, other than maybe having to spray them down with water to remove any bird droppings. 

  • The ability to capture enough sunlight depends on the orientation of your house, how much sun you receive, whether or not you have trees or adjacent buildings creating shade, the slope of your roof, and the surface area of roof you have to add panels to. 


    Southward facing home with 46 solar panels
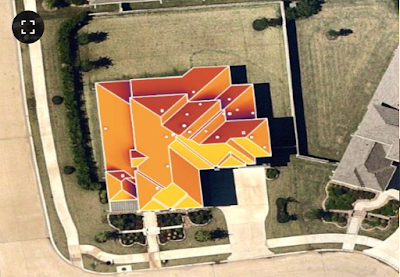
     
    Heat map - yellow = most exposure = most efficient; dark orange = least exposure = lease efficient


  • Some solar companies can only build you a system that does not exceed 10% of your power utilization. They use the previous year's energy bill and consumption in kilowatt hours as a guide. 
    • I take issue with this because the older your home gets, the less efficient it is. Additionally, if you had problems with energy consumption in the past year, your data may not be as accurate. A system built today may not be appropriate for your usage in 5 / 10 / 15 years. 

  • Unless you live on a farm or out in the middle of no where, you have to remain connected to the energy grid. A battery is really only good for storing energy in case the power goes out. I learned that if there is a power outage, because you are still connected to the utility and the solar power feeds the utility lines automatically, if there is a power outage, the solar system shuts down automatically. So there's not really an option to be living a battery-powered life. In any event, a single battery costs about $9-15k. So tack that on to the cost of your system. And likely, you will need more than 1 battery if your home exceeds a certain size. 

  • The cost of the system itself depends on the amount of energy you will need to create and the amount of space that you have to lay out solar panels to create and store that energy. In general, the bigger the house, the more energy consumed, the more panel you will need. 
In our case, we averaged somewhere in the range of 1500-2000 kilowatt hours of consumption over the past year which ranged in cost from $175 to $225 per month. The solar panels necessary to run our home at this rate would cost us about $36,000 for the panels alone, and that's paying it up front (not a loan) and getting the 26% federal tax credit (which comes when you file your tax return). So the cost of cash out the door on day one is really +/- $48,000 and then you have to wait to get your credit when you file your tax return. If I added a single battery, the cost would be an additional $12,000; two batteries would cost $19,000 (both before tax credit). 

There are other options that the solar companies offer. The one that draws the most attention is the $0 due at signing / no cost today. Essentially what happens is you can finance the cost of your system over 10 or 20 years. The interest they charge is 2.99% for 10 or 4.99% for 20 years. And you, instead, have a monthly payment to make to the solar company rather than the utility. So you end up paying more, obviously. The $36,000 system will cost roughly $44,000 by the time you're done paying it off.

My first issue with this is if I wanted to finance the cost of my solar panels, the better option would be to take out a home equity loan or borrow against my home. With interest rates so low these days, I'd get a better deal that way. 

My second issue with financing is if you choose the longer option at 20 years to avail of a lower monthly payment, by the time you're done paying for the system you've reached nearly the end of the life of the panels. By that time, you'll have to replace panels or worse yet replace the entire system. Have you really saved any money then? Or are you just breaking even? 

Also note: solar panels are not a home improvement. They are considered tangible personal property and not a fixture of the house. That being said, they do not improve the value (financially) of your home. In fact, if you wanted to take the solar panels with you to your next home, in theory, you could. But solar companies still advertise that having a solar system will increase the value of your home. I suppose it could, if the buyer of your home was willing to purchase the panels from you, but they could easily say they love the house but not the panels and have you remove them before you sell. In which case, you've got to shell out the money to have them taken down, and then there's no guarantee that they'll fit on the new home you're moving into. 

My problem now is one that's moral and ecological. While I know that becoming self-sufficient from an energy perspective will help the environment and that installing these panels would be doing our part in "saving" the world, my financial logic is at war with my conscience. I cannot justify the cost mathematically. The cost vs. (financial) benefit is about even. But the (financial) cost vs. (climate change) benefit is heavily in favor of adopting a solar energy system. 

Have any of you gone down this decision path? If so, please feel free to share your insights. And if I've gotten anything wrong up there, please help me understand so that I can correct my thinking. Many thanks! 

Sunday, December 10, 2017

Is There A Way To Encourage Healthy Eating (and Living)? - The Shock Of A Lifetime


Is there a way to flip the pricing / cost of healthy and non-healthy food to make the good stuff cheaper and the bad stuff more expensive so that we can eat healthier without worrying about cost?

It's a matter of supply and demand, I know. But will we ever get to the point where the demand for healthy, organic foods is greater than the demand for over-salted or high sugar content processed foods? Or will the supply for good-for-you food ever surpass the supply of off-the-shelf, ready-to-eat packaged goods? 

I have no idea really, but I'd hope that something drastic happens in my lifetime.

Here's an example of something that bothers the heck out of me.

Strawberries.

Amazon Fresh has 1 pound of regular strawberries for $3.99, while they carry organic strawberries for $5.99. You have to pay a $2 premium to eat better quality food.


I think it would take an enormous one-time shock to the systems (financial / economic / agricultural, etc.) for anything to change.

There has to be a way. So what if, for example, organic fruits and vegetables were produced in mass and the price could be driven as low as other non-organic fruits and vegetables? Then in theory, the demand for organics could potentially be what non-organics are currently. At the onset, obviously, the supply wouldn't be enough to feed the masses. But after a potential spike in cost until farmers could supply the demand, prices would come back down to affordable, reasonable levels. 

Or what if farmers just stopped producing non-organic fruits and vegetables all together? What if everything was organic? Again, it would be a temporary shock but the end result would be what I'm looking for. Mass produced, organic fruits and vegetables at inorganic prices.

Regular bagels
Whole Wheat bagels
Stepping away from the organic / inorganic conversation, how about just making a decision between healthier options of the same product? Let's take breakfast for example.

Bagels. If you're from the Northeast, you know this is a staple breakfast item. Whether you buy it from your local bagel store, a street vendor, or your local grocery it rarely disappoints.

For a 6-count package of Thomas' plain bagels on Amazon, you would need to pay $3.49. Add some Philadelphia Cream Cheese, a regular 8oz tub, and that's another $2.99. All together, that's $6.48. But if you so happened to be in a healthier mood and wanted to trim some fat and eat whole grains, your option would likely be for Thomas' 100% Whole Wheat bagels and the 1/3 less fat version of cream cheese. A 6-count would be $4.94 and the 8oz tub is an additional $4.39. The total comes to a staggering $9.33. That's a premium of $2.85 to eat a marginally healthier meal (see the nutrition labels). 


Regular cream cheese
1/3 less fat
What about McDonalds? Let's take a look at 2 sandwiches that they offer and compare the relative healthiness and cost. The All-American Double Cheeseburger versus the Artisan Grilled Chicken Sandwich. We all know that chicken is leaner; grilling is better than frying; white meat is better than red meat. The chicken sandwich sits on McDonald's menu at a price of $4.39, while the double cheeseburger is a value-meal at a measly $1.69! 

And take a look at these nutrition facts. Clearly the Artisan Grilled Chicken is a better choice for health purposes. But of course, it's at a premium. 

Artisan Grilled Chicken Nutrition Facts

Double Cheeseburger Nutrition Facts

Alternatives to regular, unhealthy food are the key to a healthy living. But healthy options are, unfortunately, more expensive in the marketplace. When good food becomes the primary sustenance, the cost relationship should flip. 

Sadly, I find this predicament true of not just the food industry but also the energy industry (alternative / renewable energy > fossil fuel). There are plenty of other situations, industries, and products where the current "alternatives" are better for people and the environment but are more expensive than regular products. Clearly, we need change. 

If we really wanted to encourage healthy eating, we'd find a way to make it cheaper and require less cost-benefit thought. Good food should be a no-brainer. But how can we make alternatives the primaries? 

Maybe like the heart attack that jolts a man to changing his poor eating and healthcare habits from bad to good, a sudden shock to our financial, economic, and agricultural systems is all we need to drive a healthier lifestyle going forward. 

Wednesday, December 6, 2017

ANALYSIS: My Tax Reform Impact


Just for the sake of comparison, to see what the potential impact would be to our personal Federal tax returns, I did a quick analysis of the major points from tax reform against my 2016 filing (married filing jointly).

The issues with direct impact to our tax returns are:
  • Repeal of the State & Local (SALT) Deduction
  • Property Tax Deduction Limit at $10K
  • Mortgage Interest Deduction - capped at property values of $500k
  • Repeal of Personal Exemptions
  • Doubling of Standard Deduction
With tax reform, when it comes to reducing our Adjusted Gross Income, we have the option of choosing the new Standard Deduction in the range of $24k or Itemizing. If we itemize, we are losing out on nearly $25k in deductions compared to what we could be getting with the current tax law. This is mostly related to the loss of the SALT deduction and the removal of Personal Exemptions. So previously where we most certainly would have itemized, we are now on the cusp of choosing the Standard Deduction over the Itemized Deduction. It's close.

This brings us to our taxable income. The change in the tax brackets put another wrench into the computation. Where we previously would have been in the 28% bracket, we could potentially be in either the 24% or 25% bracket, depending on whose rate passes (between House or Senate) or some agreed upon number. So the reduction in tax rate is helpful. What will really determine the end result is what the tax table will determine as the subtraction factor.

What do I mean? If you make over $100k, there is a multiplier and then a subtraction. So for example, if you make $100k (married filing jointly), your tax is $21,037 [($100,000 x 28%) - $6,963]. The subtraction factor is the $6,963.

If there are no changes to the subtraction factor, then our resulting tax liability could be in the ballpark of what the liability is previous to tax reform. If they make some changes to this subtraction factor, then there could be potential for greater or lesser tax due. So the impact of tax reform to my personal tax return could be minimal FOR NOW, but annoying all the same. There is plenty of potential future impact, especially in the purchase of a new home (mortgage interest, property tax) or even just borrowing against my equity, not to mention the tuition expenses that I'll have later in life for my children (potentially non-deductible now - but my hope is for tax reform again in the future to reverse this if it pushes through now).

For many others, it could be a bigger headache and a much bigger impact.

Take heed! This is only for the Federal income tax portion of the tax puzzle. We have yet to see how the states react to any Federal tax reform. If they conform to the Internal Revenue Code (IRC) or not will determine impact to our SALT liabilities. Remember, the Federal government could potentially take away from each State's own revenue. This could potentially be another detriment or benefit depending on which way each local government responds to the changes.

If you haven't already read up on it, I suggest you do. And I also advise speaking to your Tax Accountant and/or Financial Adviser to discuss your impact. Here's a few articles to read in the meantime:

- OPINION: Tax Cuts And Jobs Act - Detrimental to the Middle Class
- How your tax bracket could change under Trump's tax plan, in two charts

Wednesday, November 8, 2017

OPINION: Tax Cuts And Jobs Act - Detrimental to the Middle Class

I recently read a summary produced by Ernst & Young of the latest tax reform bill called the Tax Cuts and Jobs Act. The bill is the work of some Republicans looking to overhaul the tax system, something that hasn't been done in 30 years. The proposal addresses a number of things including but not limited to corporate tax, partnership tax, international issues, the insurance industry, pensions / retirement, accounting methods, and most importantly individual taxes. 

My first thought is that the offerings and eliminations are too numerous to enact in a single sitting. I'm not surprised, since the GOP has been looking for ways and means to get a tax bill passed for the longest time. In my opinion, if the government wants to make change, it should do so in steps. This all-in-one pitch is likely to have missteps and eventually gaps that will be detrimental instead of helpful. 

If you haven't been paying attention, this is the time to do so. My reading of the highlights quickly angered me in more ways than one. And I'm sure you will feel the same. I seriously hope that this bill is rejected and better propositions are given. I think the nature of this proposed act is more beneficial to the wealthy and corporate, rather than the middle class. Let me try to identify why. While I have some gripes with corporate tax and know it will be a large headache in the short term (for me as a corporate tax accountant), I'll concentrate on individual taxes for now for the sake of this post. 


Here are a few of the things that I found particularly annoying that primarily affect the middle class:
  • The standard deduction is proposed to be increased to $12,200 for singles and $24,400 for couples. BUT they are doing away with the personal and dependent exemptions. So a single filer as it currently stands can take $6,350 as a standard deduction with a personal exemption of $4,050. That equates to $10,400 in deductions. The changes would only net you $1,800 more in deductions. AND if you have a dependent, that would have been $4,050 more in deductions which would be in excess of the new $12,000 standard. So for families, each child you have would NOT be produce a deduction in the proposed tax plan. That's a major detriment in my eyes.
  • The act is looking to repeal the state and local tax deduction. If you live in a state that applies income tax, then you are paying taxes on your hard-earned income to that state. That payment currently can be deducted if you itemize. Depending on which state your reside, state tax rates can be as high as 12%. For some people, the state and local taxes that they pay are in excess of the proposed standard deduction. Yet another detriment for the middle class people.
  • Republicans are also looking to limit the deduction allowed for real estate taxes paid. Where currently, you can deduct all the tax you pay for your property, the suggestion is that only $10,000 of real estate tax will be deductible. If you live in the Northeast or any high property tax area, this is going to be an issue. You'd be forced to leave a deduction that was historically allowed on the table yet again if tax reform is passed.
  • The proposal also calls for reducing the cap on the mortgage interest deduction. This means new buyers can deduct interest on loans only up to $500,000, down from $1 million. Anything in excess of $500K that you would be paying interest on would not be allowed as a deduction.  Additionally, homeowners will only be able to deduct interest on the mortgage for their principal residence, meaning you won't benefit from this tax break if you have a vacation home like in current law. Sounds like a penalty for the upper-middle class.
    • You'll also want to think twice about taking out a home equity loan or line of credit, as the bill won't permit you to deduct the interest either. Looks like you're not going to want to build out that extension of your home, or add a deck, or borrow against your house to take that vacation or pay for college tuition. Talk about limiting!
  • The deduction for casualty loss would be repealed. So for those of you who are affected by hurricanes, fire and other disasters that are not compensated by insurance you're at an even greater disadvantage thanks to your Republican tax lawmakers if the bill is passed.
  • Tax preparation expenses, alimony payments, and moving expenses (although limited now) are looking to be cut out of the tax code completely, and therefore non-deductible in any way.
  • Repeal of education provisions:
    • Deduction for interest payments on qualified education loans for qualified higher education expenses of a taxpayer, the taxpayer’s spouse, or dependents
    • Deduction for qualified tuition and related expenses
    • Exclusion from income of interest from US savings bonds used for qualified tuition and related expenses
    • Exclusion from income of qualified tuition reductions provided by educational institutions to their employees, spouses, or dependents
    • Exclusion from income of employer-provided education assistance
    • This all spells disaster for students who are already reeling from the sky high cost of secondary education in America. And this will have a snowball effect. Instead of encouraging learning, potentially bright students will shy away from racking up debt. That will diminish the potential of the education system and at some point reduce the educated workforce. Not good.
Then there are the proposed changes that seemingly benefit the wealthy. What for?
  • Alternative Minimum Tax (AMT) would be repealed. Why? They take advantage of every single tax break and often times end up not paying tax. Shouldn't they have a minimum to help do their part?
  • The tax brackets are changing. Currently, there are seven tax brackets: 10 percent, 15, percent, 25 percent, 28 percent, 33 percent, 35 percent and 39.6 percent. The proposal is consolidating brackets, so the remaining will be: 12 percent, 25 percent, 35 percent and 39.6 percent.
    •  What does this mean? It means that the wealthy are actually getting a break! For example, a couple who is making $500,000 is subject to 39.6% currently. The new plan would afford them a discount to 35% as the highest income bracket would not begin until you hit the $1M mark. Unreal!
  • The estate, gift, and generation-skipping taxes initially would be retained with a doubled $10 million basic exclusion, but after 2023 the estate and generation-skipping taxes would be repealed (with a stepped-up basis in property) and the top rate on the gift tax would be reduced to 35%. That's a big deal from an estate planning perspective. 
Sounds like the winners are the super wealthy and the heirs to their estates.

What I'm trying to point out is that, in my opinion, if you are in the middle class, you have more to lose than to gain. This proposed tax bill and reform are lopsided. A majority of Americans are in the low to middle class and this act doesn't benefit the people who make American great. Instead, Republican tax lawmakers are penalizing the vast majority for their hard work and dedication. Find a different way because this proposal will not work. 

And for us, the middle class, this is an opportunity to push back. We cannot just accept change and work around it. We'll be hurting ourselves and our families in the long run if this bill is enacted. (1262)

Wednesday, September 13, 2017

Your Parents' Financial Well-Being - And Yours Too!

If you're in your 30s, and you have parents who are nearing retirement or who are getting older and less able to make wise decisions, then it's my advice to you to check on their financial well-being. Heck, if you're in your 30s then you better make sure that you're capable of managing your own money and understanding what everything is and means.

This post comes as a warning to all my readers, friends, and family just based on recent experience with my own parents.


I have an Accounting background by education and profession, so I like to think that I'm fortunate enough to be a little more financially savvy than some people. It also helps that I read through and try to understand any and all money matters that I encounter. You should too! Don't just glaze over something. Make sure you understand what you're receiving or paying for.

I think a huge problem with Baby Boomers and Generation X is that they didn't have the resources to educate themselves on all the financial opportunities available to them. These generations didn't have as many reliable people to guide them to make good decisions. And a lot of information was relayed by word of mouth from others who were just as inexperienced or unfamiliar with the topics as the next person.

That being said, today was one of many days in trying to assist my parents with their situation, concerns, and planning. While having a discussion with my mom about her and my dad's future plans about retirement, money, and timing of it all, I could not help but be annoyed / frustrated and even in disbelief at some of the things we were talking about. So I compiled a few suggestions / thoughts for others who may be able to help their own parents, friends, and family.


  1. The older they are, the simpler it needs to be. Less is more. Close bank accounts. Forego using too many credit cards. In both of these situations, I like the number 2. Two bank accounts and two different credit cards are more than enough to get them through old age and retirement. My dad hates to "put all [his] eggs in one basket" so 2 of each breaks it up enough in my opinion.
  2. It's hard to remember all those passwords. Along the same lines, once you've reduced the number of accounts open, you'll have also cut down the number of Usernames and Passwords required to be committed to memory. Because let's face it, memory deteriorates with age. If there are any other accounts you can help them close, you're only helping yourself for the future.
  3. Take inventory. Since memory fails more often, you should probably help your folks keep track of their passwords, account numbers, PINs, etc. in a safe place, of course. Whether it be by pen and paper or an Excel spreadsheet, you've got to help them organize and keep track of what they have. And if they have to use the "forgot password" function, make sure to have them update their records.
  4. Money doesn't grow on trees! Believe it or not, it's possible that your parents don't know where all their money is coming from. It is also possible that they don't know who they are paying or why. So once you've taken inventory (or maybe in parallel with taking inventory), you should help organize the to/from of their income and expenses. If they're anything like my parents, they will have a recurring expense (or two, or three) that they'll have no idea the reason or the recipient. You may uncover a long forgotten 401(k) that was never rolled over from a previous employer. You may realize that they're paying for something that is a duplicate of something else. And they may surprise you with the amount they've got stashed away. 
    • Things to pay attention to: 
      • 401(k) / 403(b)
      • Traditional & ROTH IRAs
      • Investment Portfolios (especially if they have multiple brokerage accounts)
      • Multiple Bank Accounts (some seldom used)
      • Foreign Accounts (bank / investment)
      • Automated / Recurring withdrawals on their checking / savings accounts. Make sure to check monthly, quarterly, and annual frequencies.
      • AutoPay on their credit cards (monthly, quarterly, annual)
      • CDs (certificate of deposit)
      • Safety Deposit boxes
      • Pension and any other Retirement accounts
      • Annuities
      • Life Insurance policies
      • AD&D Insurance policies
      • Disability Insurance policies
      • Other Insurance policies
      • Social Security or Supplemental Security Income
      • Medicare / Medicaid
      • COBRA
  5. Plan it out. Brush up on your Excel skills and draw up a budget for them. Show them what they will have in income and budget out their expenses. If you can find ways to cut down their expenses, make sure to follow through with the processing and not just suggest it. Don't forget to leave them some money to play with. After all, they've earned it! 

In my opinion, the earlier you get started on these processes, the better off you are, not to mention your parents. I think at first they will be apprehensive and may even feel as if they're still capable. But the reality is that their abilities will degenerate faster than you think with every passing year. At the onset, you have to convince them that this is for their own good. They may thank you later, or they may just leave you some of what they've saved! 

It's an arduous process, but good luck! 

Monday, June 26, 2017

American Dream?


Ever since we returned home, all I can think about is how challenging the American Dream really is to achieve. There are many other people around the world who imagine that coming to the United States would make their lives so much easier or allow them to live with so much more freedom. While that is a true change for some people, others should really stay where they are because of how good their lives would / could be in their country of origin.

I've told countless people abroad that their perception is not reality. How so?

Some people have said to us that they believe there is so much freedom in the USA. And I've replied that yes, there are freedoms, but there are so many laws, rules, regulations, by-laws, and other stipulations that need to be abided by while living here in the USA. When I asked them if they have such regulations, many were quick to think and respond that there was no such law in their home country.

When the case of education came up, many cities and countries have found ways to make education free for their citizens. If not free, then at least it was very inexpensive which allowed for many common people to become educated without breaking the bank. When I told them the local currency equivalent of an average education in the United States, these people were sticker shocked at the absurd amount necessary to obtain a diploma.

For me, the follow up to education was logically the issue of debt. Students in the United States expend so much of their capital on education, and then suffer through unemployment or subpar work because either the market for their chosen profession is oversaturated or they are still not qualified for the work they intend on doing. Then the vicious cycle begins. They can't pay their debt, interest is added, time passes, their total debt increases. And once they obtain a decent paying job, these new workers want to enjoy their money. Many spend on clothes, cars, entertainment, and food which leaves little to pay down their initial debt in the first place. And the cycle continues. Debts and interest compound making it years before a former student can ever be relieved. And as their lives progress, their debts seemingly always increase. The next steps of their lives leads to significant others, then engagements and wedding, followed by growing families. Americans live by constantly owing someone or some institution a sum that reduces at a fraction of the speed at which it grew (exponentially). 

So what have the people around the world said? Many have said their piece to me about credit and credit cards. The main issue is, "how can you spend money that's not yours?" Or they wonder, how can the government or financial institutions allow people to have such tremendous debt? Others have expressed concern over the impact it has on the mindset of the people and the cyclical nature of the system. And for me, I've identified another issue with debt. The idea of debt prevents many capable people of pursuing education for the sheer fear of having debt and the inability to pay it off. And uneducated people means a lifetime of poverty (relative to their environment) and/or future struggles; yet another unfortunate cycle that stems from an unfortunate cycle. 


Which leads me to my real point. I am an American by birth, but a citizen of the world in mind and in heart. And I've been thinking so much about my American Dream. For many years, I wanted to follow in the path of the majority. I wanted to graduate from a top notch university; I did that. I wanted to own a car; I paid it off in 4 years rather than 5. I wanted to own a home and grow a family. And this is where I've stalled somewhat.

At the age of 24, I purchased my first home, and I am currently financing it over 30 years (21 left) with some moderate interest rate. I spend a fairly good chunk of my salary paying for this home. But I spend most of my time in an office over an hour away from the home where my money is sunk. How on earth is this a justifiable way spend hard earned money? 

Is this really the dream I wanted? No way! Why am I spending hundreds of thousands of dollars on a place where I spend less than half of my time? Why am I trying to fill my home with dead space or useless items of decoration? Why am I struggling to spend on other things that matter like continuing education, organic food and better health, or life experiences and culture? 


I am having a hard time coming up with good reasons to keep doing what I'm doing for the reasons that have previously been dictated by popular culture or merely precedent, here in the USA. 

I feel a change coming... 


Wednesday, March 27, 2013

So Long, Farewell, Auf Wiedersehen...

Goodbye!

Today I sold Camy, my 5 year old Toyota Camry.


A side of me is sad to part with her, but I know that financially it made sense. I'll be saving on insurance, gas, tolls. But most of all, I will not be watching her depreciate while sitting in the parking lot enduring the variety of weather.

We just were't using her as much anymore. She had extremely low mileage (only 42k) for a 5 year old car. And so, I got a good price for her.

In the end, after all the math is said and done, it only cost me $190 per month plus insurance, gas, and tolls to own her.

She's served me well...